Analysis and report by Ross Harvison and Murali Rajagopalachari (ISM-Houston Business Survey Committee)
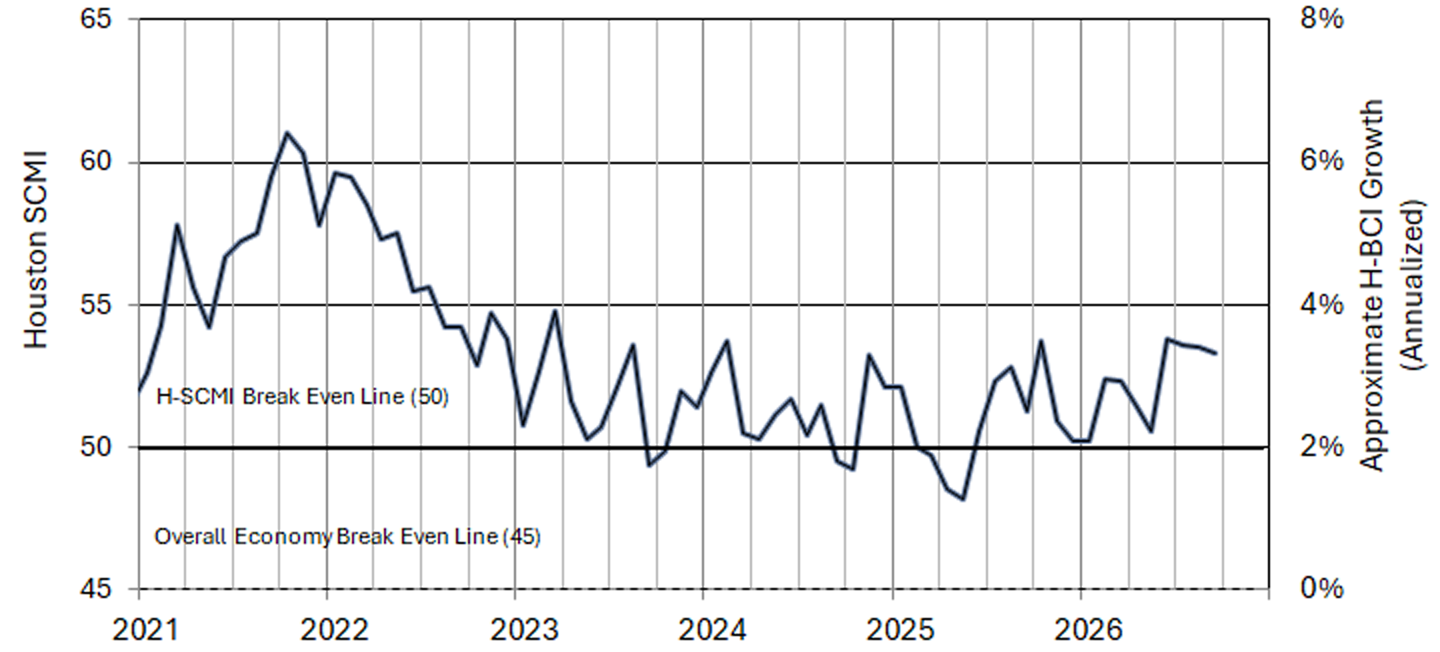
Houston SCMI at 53.3 (down 0.2 points)
Sales/New Orders Expanding
Production Expanding
Employment Expanding
Prices Paid Expanding
Lead Times Expanding
Finished Goods Inventories Expanding
(Houston, Texas) – According to Houston area supply chain executives, the Houston economy expanded again in September. The manufacturing sector moved back to contraction after only one month showing expansion, and non-manufacturing activities expanded for the eighth month. The overall Houston economy expanded for the 76th month in a row.
The Houston Supply Chain Managers Index fell 0.2 points to 53.1, indicating continued strong growth in the overall economy. All three of the underlying indicators that have a strong direct correlation with economic activity (sales/new orders, employment, and lead times) are continuing to point to modest to strong growth. The sales/new orders index rose 2.8 points to 55.0 points, the employment index fell 0.4 points to 53.0, and the lead times index fell 4.1 points to 53.0 points. The finished goods inventory index, the underlying indicator that has the strongest inverse correlation with economic activity, rose 0.7 points to 50.7 points, which indicates a very modest move towards overall economic contraction.
The Houston Manufacturing SCMI fell 1.9 points to 49.8 points. Durable goods manufacturing recovered modestly but is still pointing to significant contraction. Non-durable goods continued to show modest growth at a level similar to last month. The non-manufacturing SCMI rose a minimal 0.1 points to 53.9, indicating minimal weakening from last month.
On an industry specific basis oil and gas, professional services, construction, health care, non-durable goods manufacturing, trade/transportation/warehousing all reported modest to strong expansion. Durable goods manufacturing continues to report significant weakness.
Note that beginning with the July report the Houston Affiliate of the Institute for Supply Management changed the name of the index produced as part of this report to the Houston Supply Chain Managers Index (HSCMI) to recognize the input of a broad group of Supply Chain Leaders in the business survey that is used to develop the report. The analytical methods used to calculate all indices are unchanged.
Click here for the hard copy version of this report.
Houston SCMI Trend
Indices at a Glance
Houston SCMI readings over fifty indicate that respondents see their activities as expanding. An H-SCMI above 45 normally correlates with expansion of the Houston-The Woodlands-Sugar Land Business Cycle Index.
| Index | Sep | Aug | Change | Track | Rate | Trend* |
| Houston Overall PMI | 53.3 | 53.5 | -0.2 | Expanding | Slower | 16 |
| Houston Manufacturing PMI | 49.8 | 51.7 | -1.9 | Contracting | Fr. Exp. | 1 |
| Houston Non-Manufacturing PMI | 53.9 | 53.8 | 0.1 | Expanding | Faster | 8 |
| Sales/New Orders | 55.0 | 52.2 | 2.8 | Expanding | Faster | 9 |
| Production | 53.2 | 51.9 | 1.3 | Expanding | Faster | 4 |
| Employment | 53.0 | 53.4 | -0.4 | Expanding | Slower | 8 |
| Purchases | 52.0 | 51.0 | 1.0 | Expanding | Faster | 33 |
| Prices Paid | 57.1 | 57.0 | 0.1 | Expanding | Faster | 12 |
| Lead Times | 53.0 | 57.1 | -4.1 | Expanding | Slower | 10 |
| Purchased Inventory | 48.9 | 45.8 | 3.1 | Contracting | Slower | 2 |
| Finished Goods Inventory | 50.7 | 50.0 | 0.7 | Expanding | Faster | 2 |
| Overall Houston Economy | Expanding | Slower | 76 | |||
| * Number of months on current track | ||||||
Commodities Reported to be Up/Down in Price or in Short Supply
Up in Price: Tariffs; general labor; crude oil, gasoline, diesel, jet fuel, propane, natural gas, natural gas liquids, ethane, propane, normal butane, isobutane, natural gasoline, naphtha; imported finished goods, films, chemicals, rhodium; pipe, steel, hot rolled coil; power generation; computer components; truck drivers, transportation and distribution services, dry bulk freight, ocean container freight from Asia.
Down in Price: Gold, lumber.
In Short Supply: E&I technicians; resins, lab supplies; transformers, power generation, compression, control panels; memory chips, processors; tungsten, yttrium.
‡ Noted as being up or down by different respondents.
What Our Respondents Are Saying:
Oil and Gas Exploration, and Key Support Services:
- Texas rig counts continue to rise at a modest pace.
- Tariffs, geopolitical, and rare-earth mineral issues are of concern.
- Crude prices continue to fluctuate greatly due to the Iran conflict.
- This sector reported expansion for the third month. The sales/new orders, employment, prices paid, and lead time indices are all pointing towards moderate to strong growth.
Construction:
- Many large capital projects are underway in the US that require or incentivize buying domestically, so the supply chain is expected to be strained to meet the demands.
- This sector weakened somewhat during the month but continues to experience strong expansion. The sales/new orders and employment indices moderated to just above neutral, while the prices paid and lead times indices remained very strong.
Durable Goods Manufacturing:
- Incoming orders have increased due to increased oil/natural gas activity, and due to rising demand and increased orders from the Aerospace industry.
- This sector continues to report significant weakness. The sales/new orders and purchases indices joined the prices paid index near neutral. The production and employment indices continued to point to contraction.
Non-durable Goods Manufacturing:
- US continues to be strong with exports.
- We are seeing inventories begin to rise again and that’s a good thing as chemicals were really scraping the bottom of supply. The supply and demand curve is still far from balanced.
- No major changes. The general political instability continues to impact the industry.
- Natural gas and motor fuel prices continue to rise.
- Petrochemical feedstock prices rose across the board (ethane, propane, butanes, and natural gas liquids).
- While cracking feedstock prices rose significantly, we have seen very flat polymer prices.
- This sector weakened somewhat during the month but continues to point to expansion. The sales/new orders, production, purchases, prices paid, and lead times indices all showed strength. The employment index continues to point to considerable weakness.
Trade, Transportation, and Warehousing:
- Tariffs continue to have an impact on price paid and uncertainty is slowing consumer demand.
- Employment is up this month as previously held recruitment decisions have been released given the need for additional labor and no change in the uncertainty.
- Container freight rates from Asia continue to rise.
- Diesel prices are still driving uncertainty in the trucking space.
- Truck carriers are reporting increasing driver shortages as drivers are finding strong pay staying in their home market instead of working long haul.
- This sector reported moderate expansion again this month. The employment and prices paid indices both showed strength, while the sales/new orders and purchases indices were reported just above neutral. All other indices came in at neutral.
Real Estate:
- This sector reported near neutral this month with all indices reporting near this level.
Health Care:
- Transportation and distribution activities are under significant upward pressure.
- This sector reported continued strong expansion with the prices paid and lead times indices showing significant strength. All other indices reported near neutral.
Professional and Business Services:
- There continues to be ample supply of qualified people either looking for work or seeking to work someplace other than their current employer. The only exception is for positions that require very specialized experience and backgrounds that are causing pockets of more demand than supply.
- Salaries and hourly contractor rates remain steady, with companies pushing to pay less when they can. We see this on many non-technically qualified individuals.
- Not any significant movement when speaking of pay.
- Business in Houston remains “uncertain.” A combination of the upcoming elections and the world situation. This situation goes beyond just the Iran war and includes concerns regarding food sources, prices, attitudes on clean energy, social and political implications, it is a very complex world economy. A wait and see attitude is expected.
- This sector reported strong expansion with the sales/new orders and employment indices continuing to be reported as expanding.
Trend of Underlying Indicators
Sales/New Order Index
The sales/new orders index rose 2.8 points to 55.0 points during the month. Both non-manufacturing and manufacturing reported expansion in this index.
| Sales/New Orders | Higher | Same | Lower | Net | Index |
| Apr 2026 | 17% | 78% | 5% | 12% | 53.5 |
| May 2026 | 11% | 84% | 5% | 6% | 50.3 |
| Jun 2026 | 23% | 72% | 5% | 18% | 59.4 |
| Jul 2026 | 16% | 79% | 5% | 11% | 56.5 |
| Aug 2026 | 10% | 83% | 7% | 3% | 52.2 |
| Sep 2026 | 12% | 83% | 5% | 7% | 55.0 |
Production Index
The production index rose 1.3 points to 53.2. While non-manufacturing remained just above neutral, manufacturing showed much stronger growth in this index.
| Production | Higher | Same | Lower | Net | Index |
| Apr 2026 | 5% | 93% | 2% | 3% | 50.4 |
| May 2026 | 5% | 90% | 5% | 0% | 48.9 |
| Jun 2026 | 8% | 87% | 5% | 3% | 52.2 |
| Jul 2026 | 9% | 87% | 4% | 5% | 52.2 |
| Aug 2026 | 8% | 89% | 3% | 5% | 51.9 |
| Sep 2026 | 8% | 89% | 3% | 5% | 53.2 |
Employment Index
The employment index fell 0.4 points to 53.0, indicating continued moderate expansion. Non-manufacturing came in above neutral and manufacturing continued to report well below this level.
| Employment | Higher | Same | Lower | Net | Index |
| Apr 2026 | 8% | 88% | 4% | 4% | 50.7 |
| May 2026 | 8% | 86% | 6% | 2% | 50.5 |
| Jun 2026 | 13% | 79% | 8% | 5% | 51.4 |
| Jul 2026 | 12% | 80% | 8% | 4% | 52.2 |
| Aug 2026 | 11% | 82% | 7% | 4% | 53.4 |
| Sep 2026 | 9% | 85% | 6% | 3% | 53.0 |
Purchases Index
The purchases index rose 1.0 points to 52.0 points. Non-manufacturing remained near neutral while manufacturing rose to well above this level.
| Purchases | Higher | Same | Lower | Net | Index |
| Apr 2026 | 19% | 75% | 6% | 13% | 53.8 |
| May 2026 | 20% | 74% | 6% | 14% | 55.1 |
| Jun 2026 | 18% | 75% | 7% | 11% | 55.5 |
| Jul 2026 | 20% | 78% | 2% | 18% | 58.9 |
| Aug 2026 | 10% | 81% | 9% | 1% | 51.0 |
| Sep 2026 | 8% | 86% | 6% | 2% | 52.0 |
Prices Paid Index
The purchases index rose and minimal 0.1 points to 57.1 with non-manufacturing relatively unchanged and manufacturing reporting continued strength at a level similar to last month.
| Prices Paid | Higher | Same | Lower | Net | Index |
| Apr 2026 | 34% | 64% | 2% | 32% | 64.3 |
| May 2026 | 35% | 63% | 2% | 33% | 65.1 |
| Jun 2026 | 23% | 74% | 3% | 20% | 61.4 |
| Jul 2026 | 24% | 74% | 2% | 22% | 62.3 |
| Aug 2026 | 17% | 81% | 2% | 15% | 57.0 |
| Sep 2026 | 20% | 78% | 2% | 18% | 57.1 |
Lead Times Index
The purchases index fell 4.1 points to 53.0 points with manufacturing reporting moderately lower strong expansion in this index and non-manufacturing reporting just above neutral.
| Lead Times | Higher | Same | Lower | Net | Index |
| Apr 2026 | 7% | 91% | 2% | 5% | 51.0 |
| May 2026 | 9% | 86% | 5% | 4% | 51.3 |
| Jun 2026 | 8% | 89% | 3% | 5% | 52.7 |
| Jul 2026 | 14% | 80% | 6% | 8% | 53.3 |
| Aug 2026 | 15% | 83% | 2% | 13% | 57.1 |
| Sep 2026 | 11% | 85% | 4% | 7% | 53.0 |
Purchased Inventory Index
The purchased inventory index rose 3.1 points to 48.9 with non-manufacturing reporting just above neutral again this month and manufacturing reporting contraction in this index at a slower pace than last month.
| Purchased Inventory | Higher | Same | Lower | Net | Index |
| Apr 2026 | 4% | 90% | 6% | -2% | 49.2 |
| May 2026 | 3% | 93% | 4% | -1% | 48.1 |
| Jun 2026 | 3% | 92% | 5% | -2% | 48.7 |
| Jul 2026 | 5% | 92% | 3% | 2% | 51.6 |
| Aug 2026 | 2% | 89% | 9% | -7% | 45.8 |
| Sep 2026 | 2% | 94% | 4% | -2% | 48.9 |
Finished Goods Inventory Index
The finished goods inventory index rose 0.7 points to 50.7 points with both manufacturing and non-manufacturing reporting near this level.
| Finished Goods Inventories | Higher | Same | Lower | Net | Index |
| Apr 2026 | 8% | 86% | 6% | 2% | 51.3 |
| May 2026 | 5% | 90% | 5% | 0% | 49.7 |
| Jun 2026 | 7% | 88% | 5% | 2% | 50.8 |
| Jul 2026 | 4% | 89% | 7% | -3% | 48.7 |
| Aug 2026 | 4% | 92% | 4% | 0% | 50.0 |
| Sep 2026 | 4% | 94% | 2% | 2% | 50.7 |
Houston SCMI Calculation Methods
The Houston Supply Chain Managers Index has been included as an integral part of the ISM-Houston Business Report since the Houston affiliate of the Institute for Supply Management started publishing this document in January 1995. The report and index are issued monthly as the primary deliverables from a survey of Houston area Supply Chain leaders regarding the status of key activities that provide insight into the strength of the economy. The respondents come from diverse organizations including construction, energy, engineering, health care, durable and non-durable goods manufacturing, financial and business services, wholesale and retail trade, and utilities related companies.
The Houston Supply Chain Managers Index is determined from diffusion indices of the eight indicators of economic activity covered by the ISM-Houston Business Survey and Report. These underlying indicators are sales or new orders, production, employment, purchases, prices paid for major purchases, lead times from sellers, purchased materials inventory (raw materials and supplies), and finished goods inventories. The respondents to the survey report the direction of each of these activities as either up, the same, or down in comparison to the previous month. An index for each of these areas is then calculated by subtracting the percentage of respondents that sight a negative shift from the percentage that sight a positive shift. For indicators that are positively correlated with economic growth, this results in an underlying index that points to expansion when it is above zero. Indicators that are negatively correlated with growth point to expansion when they are below zero.
The final Houston SCMI is calculated by applying optimal regression factors to each of the eight underlying indicators noted above. These regression factors are determined using standard regression techniques comparing these underlying indicators to the Houston-The Woodlands-Sugar Land Business Cycle Index (Houston BCI), which is reported monthly by the Federal Reserve Bank of Dallas. This top-level index is converted to a 0 to 100 scale to match that of the national Purchasing Managers Index® (PMI®) which is published monthly by the Institute for Supply Management® (ISM®). Readings over 50 for the HSCMI generally indicate manufacturing expansion in Houston in the near term and readings below 50 show coming manufacturing contraction.
It is important to note that the manufacturing breakeven HSCMI does not equate to the breakeven point for the overall Houston economy. ISM-Houston periodically reviews the capability of its correlations and adjusts the regression factors when appropriate. The most recent revision occurred in 2018 after it was determined that changes in the Houston economy over the previous decade had shifted the intercept of the correlation, causing a neutral Houston SCMI to no longer align with a neutral Houston BCI. A Houston SCMI of 45 points now equates to a neutral Houston economy as measured by the Houston BCI. A similar offset between the National SCMI and the National economy has existed for some time.
Use of ISM-Houston Business Report Content
All information included in this report is protected under copyright law, and ISM-Houston reserves all rights to this content. ISM-Houston grants a limited, revocable license for personal, non-commercial use, including access, printing, and display of content. Requests for permission to reproduce or redistribute the ISM-Houston Business Report content should be directed to the ISM-Houston Business Survey Committee at hSCMI@ism-houston.org.
ISM-Houston assumes no liability, obligation, or responsibility for the accuracy, completeness, or timeliness of the information contained herein. This includes any errors, omissions, or delays in providing the report. Furthermore, ISM-Houston shall not be liable for any damages, whether direct, incidental, consequential, or special, arising from the use or reliance on the information provided in this report.
ISM-Houston Business Report Background
The ISM-Houston Business Report has provided some of the best information regarding what is happening in the Greater Houston area economy for over 30 years. It delivers significant analytical data along with a summary of what Houston area Supply Chain Leaders are saying about the economy and is subscribed to by a wide range of global business leaders, economists, researchers, and reporters.
The report and index are published monthly as the primary deliverables from a survey of Houston area Supply Chain professionals. These highly engaged leaders provide information on key activities that are related to the strength of the economy. They come from diverse organizations including construction, energy, engineering, health care, durable and non-durable goods manufacturing, financial and business services, wholesale and retail trade, and utilities related companies.
We are always looking to improve our coverage of the industries that make up our economy. Please join us to help make our results even more representative of what’s happening in Houston by completing this signup form.